Tax and compliance · 16 Oct 2026
GST for online sellers
GST for online sellers: registration, the GST invoice, TCS on marketplace payouts, input tax credit and monthly reconciliation.
In short
GST on readymade garments turns on one number: the sale value of each piece. Here is how that reads on a wholesale quote and a tax invoice, line by line, and what to check before you pay.
At the time of writing, readymade garments carry GST at 5% where the sale value is up to ₹ 2,500 a piece, and at 18% where it is above ₹ 2,500. This split applies from 22 Sep 2025.
Before that date the line sat at ₹ 1,000 a piece, with 5% at or below it and 12% above. If you compare a new quote with an older invoice, the same piece may show a different rate on each.
The split covers apparel and clothing accessories, chapters 61 and 62 of the customs tariff, which GST uses to classify goods. Fabric, yarn and trims have entries of their own, so read each rate against the code on its line.
That code is the HSN code, from the Harmonised System of Nomenclature: the classification number for the goods on a line. It shows which rate entry the supplier has applied, so a wrong code is worth querying even when the rate looks right.
Rates are set by government notification, and they change. Treat this article as a guide to reading the paperwork, confirm the rate for your lot on the quotation, and take anything close to the line to your own tax adviser.
The threshold is written per piece, so it applies to the sale value of each piece, not the invoice total or the order size. A large invoice of inexpensive pieces stays at 5%; a small one of pieces above the line goes to 18%.
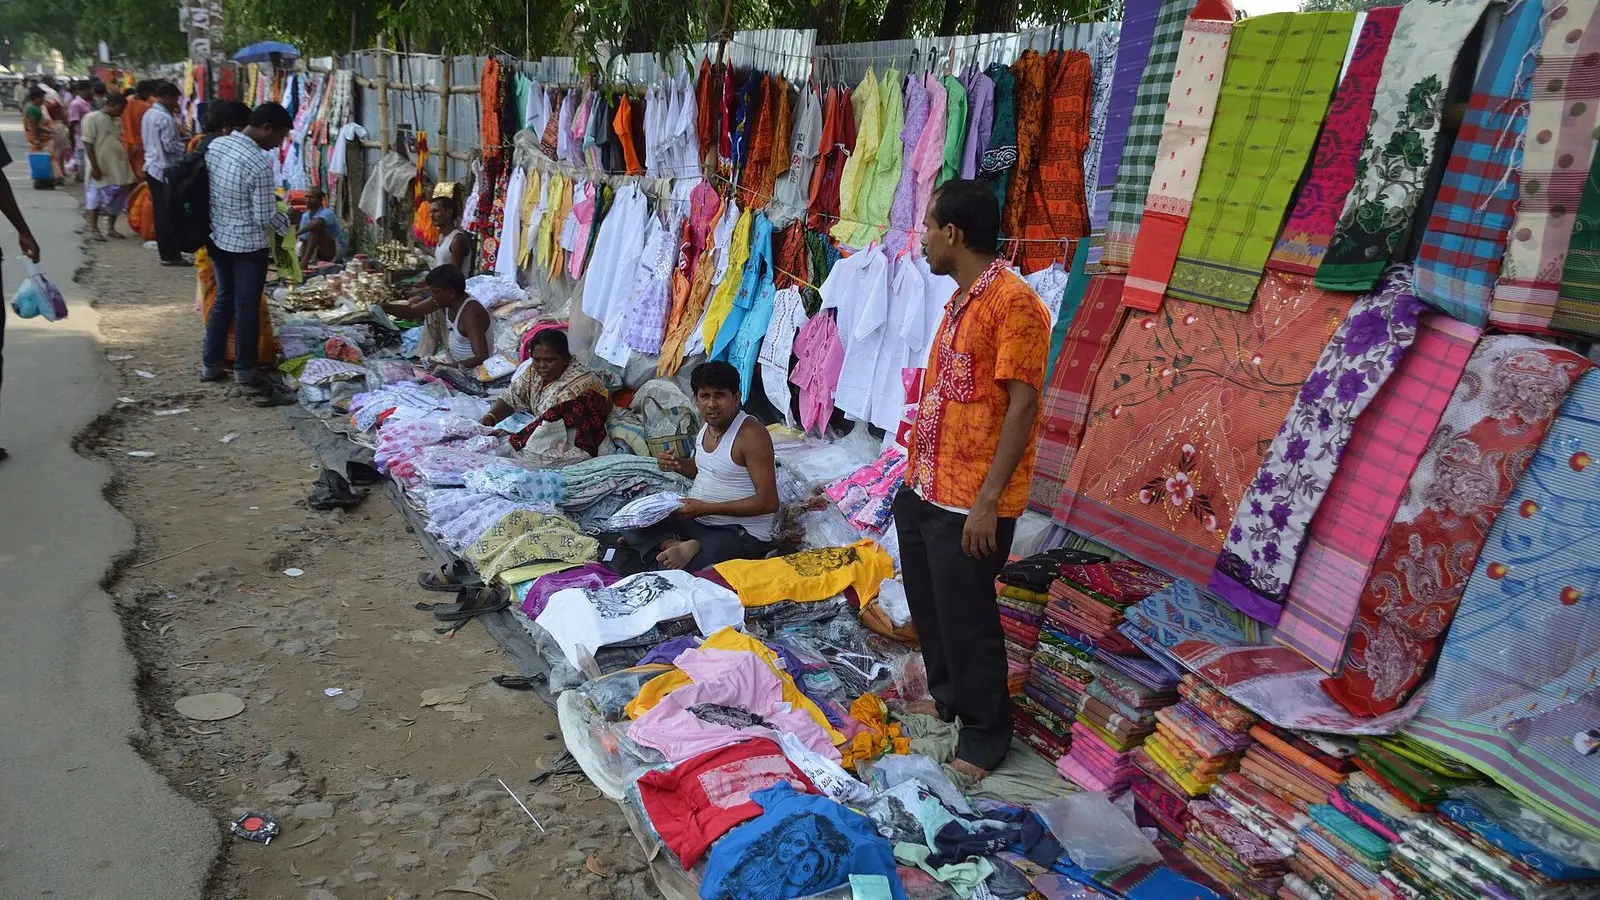
It follows that one invoice can carry both rates. A mixed lot of cotton shirts and padded jackets, with the jackets priced above ₹ 2,500, puts the shirts at 5% and the jackets at 18%, each on its own line with its own HSN code.
The value tested is generally the price before GST is added. Three other things can move a piece across the line, and each deserves a decision before you agree a price:
A wholesale quote should let you rebuild the total yourself: each style on its own line with quantity, rate per piece and taxable value, then GST at each rate, then freight. If you cannot rebuild it, ask for it in that form before you accept.
Illustration: a mixed lot in round numbers, to show how the lines fall. These are not our prices and not a quotation; they show only the arithmetic.
| Line (illustration) | Basis | Amount |
|---|---|---|
| Cotton shirts, 200 pieces | ₹ 500 a piece | ₹ 1,00,000 |
| Padded jackets, 50 pieces | ₹ 3,000 a piece | ₹ 1,50,000 |
| Taxable value | Both lines | ₹ 2,50,000 |
| GST at 5% | On the shirts | ₹ 5,000 |
| GST at 18% | On the jackets | ₹ 27,000 |
| Total before freight | Taxable value plus GST | ₹ 2,82,000 |
| Freight | Quoted separately | To be confirmed |
On the invoice, each GST line splits by place of supply. Within one state it shows as CGST and SGST, the central and state shares, in equal halves; to another state, as IGST, the integrated tax. The total is the same.
For goods that move, the place of supply is generally where the movement ends. If your transporter collects in Delhi and delivers to another state, ask how the supplier has treated the supply, and check the answer with your adviser.
The state line is easy to miss in Delhi NCR, which reaches into Haryana and Uttar Pradesh. A lot from Gandhi Nagar to a shop in Gurugram or Noida is generally an inter-state supply, with IGST; within Delhi, it carries CGST and SGST.
Separate lines let you check each cost: the goods, the tax at the rate their value attracts, and the cost of moving them. An all-in figure hides the rate, and only an invoice that shows tax separately supports a credit claim.
That credit is input tax credit (ITC), the GST on purchases that a registered business sets against the GST on its sales. Claiming it needs a proper tax invoice, the goods in hand, and the invoice reported in the supplier’s own GST return.
Freight is quoted separately because it depends on things not settled when the quote is written: your transporter, the destination, and the packed weight and number of bales. That is why a quote should say “Freight to be confirmed” rather than guess.
GST on the transporter’s own charges is a separate matter between you and them, and it does not belong on the garment lines.
The rate is set by the price of each piece, not by the size of the order.
Check the document type, both GSTINs, the place of supply, and each line’s rate against its per-piece value, then the arithmetic. Each is quick to check on the day the goods arrive and slow to put right later.
Once the supplier files their return, the invoice should appear in your GSTR-2B, the monthly statement of credit available to you. If it does not, raise it with the supplier straight away: credit you cannot see is credit you cannot use.
If part of a lot goes back, the supplier issues a credit note against the original invoice, and the GST on it falls with the value. Your credit falls by the same amount. Credit notes have time limits under GST, so settle returns promptly.
Our checklist for buying wholesale in Gandhi Nagar covers the rest of the paperwork that travels with a lot, from the packing list to the lorry receipt.
Not to buy, but to claim credit. A supplier can sell to you without your GSTIN, but the invoice is then made out to an unregistered buyer, and the GST on it becomes a cost you cannot recover.
Whether you must register depends on your turnover and how you sell. Marketplace selling brings its own registration rules, set out in our guide to GST for online sellers; settle the question with your adviser before the first listing, not the first payout.
When you resell, your sale is tested against your own price per piece. A piece bought at 5% carries 18% if you sell it above ₹ 2,500 before GST, and a sale price can bring it back below the line.
The test follows the price the shopper is invoiced at, not what reaches you after marketplace commission and fees. Price points just above ₹ 2,500 deserve a deliberate decision, made with your adviser, before they go live on a listing.
Marketplaces also collect TCS (tax collected at source) under GST from your payouts. It is not an extra tax: once it shows in your GST account, it can be used against what you owe. Reconcile it every month with the rest of the settlement.
If you are starting a clothing brand in India or building a range to sell clothes online, set your price points with the GST line in view from the first listing, not after the first sale event.
On our quotes, GST sits on its own line at the rate that applies to each style, and freight reads “Freight to be confirmed” until your transporter and the packed weight are known. The rate for your lot is confirmed on the quotation.
Our invoices are issued by Kavita Enterprises, GST-registered in Delhi under GSTIN 07CBUPK4786Q1ZD, which you can check on the GST portal before you pay.
To price a range, request our wholesale garment rate card; to see how lots are sourced and supplied, read about our wholesale garments. The same per-piece test applies to private label clothing made to your specification.
We source readymade garments from manufacturers and supply them by the lot from Gandhi Nagar, with GST and freight shown separately on every quote.
GST for online sellers: registration, the GST invoice, TCS on marketplace payouts, input tax credit and monthly reconciliation.
Which Legal Metrology declarations packaged goods sold online must carry, and where each goes on the pack and the listing.
The order of work for a new clothing brand in India: range, sampling, private label, GST, labels, first lot and channels.
Tell us what you sell and where. We reply with our questions and a scope, with GST on its own line.